


This article covers the equities chapter of NAGA's Q4 2026 Market Outlook, "The Dollar Decides", by Frank Walbaum, Market Analyst at NAGA. The full report, with 20 charts, three scenarios and a quarter-long calendar, is available as a free PDF.
Stock market outlook Q4 2026 — key takeaways
The outlook's view on equities for Q4 2026, at a glance:
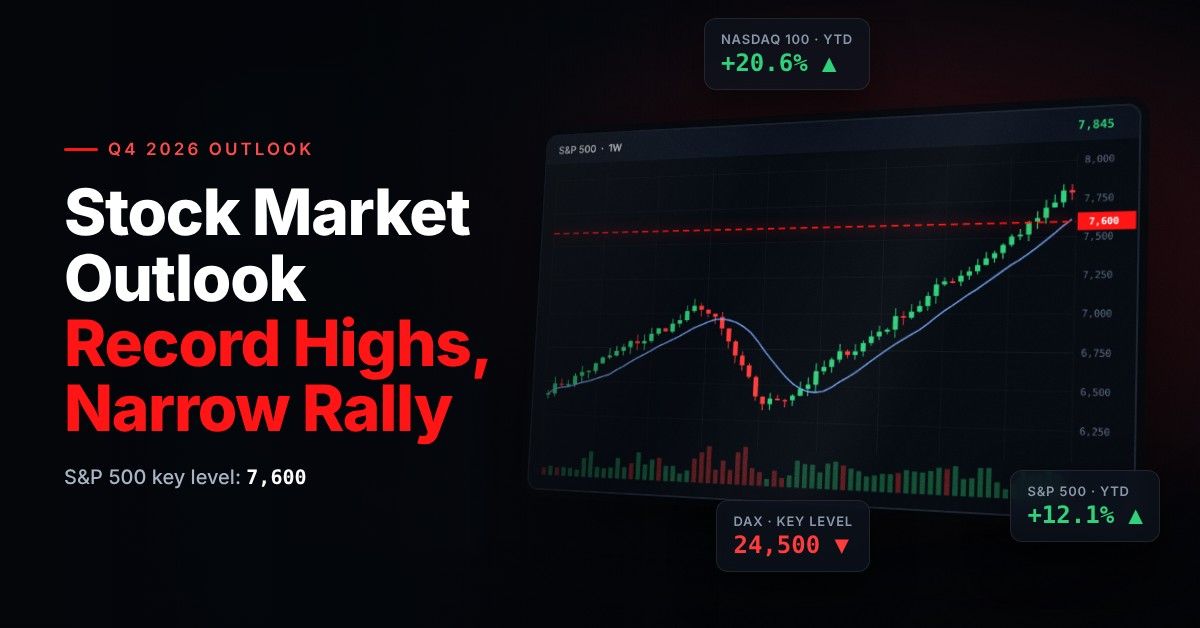
- S&P 500: neutral, a strong index with weak breadth. Key level 7,600; driven by AI earnings, market breadth and bond yields.
- DAX: neutral, with downside risk in a risk-off move. Key level 24,500; driven by global risk appetite and energy costs.
- Breadth is the warning sign. Only 46% of S&P 500 members traded above their 200-day average in early October, down from about 70% at the end of July.
- Risk-off is the most likely scenario, at 50%. Fading AI momentum, rising yields or a stronger dollar would raise the risk of a broader correction.
Each view, the scenarios behind it and the dates that could change it are explained below.
Source: NAGA Q4 2026 Market Outlook. The bias reflects the author's directional view and is not a recommendation.Open an account Practice on demo Copy lead traders
CFD trading involves risk.
Q3 2026 review: index gains on weaker foundations
US indices entered Q4 at record highs, but Q3's advance was narrow. The S&P 500 gained 2.6% and the Nasdaq 100 0.6%, while the Russell 2000 fell 7.0% and the Dow lost 2.1%.
Index Q3 2026 YTD 2026 S&P 500 +2.6% +12.1% Nasdaq 100 +0.6% +20.6% Dow Jones Industrial Average −2.1% +6.4% Russell 2000 −7.0% +12.9% DAX +0.8% +2.8% Euro Stoxx 50 −1.4% +8.2% FTSE 100 +0.3% +6.6% Source: NAGA trading platform. Q3 = 1 July open to 30 September close; YTD = 1 January open to 30 September close. Past performance is not a reliable indicator of future results.
Breadth tells the same story. The S&P 500 closed at a record in the first week of October, yet only 46% of its members traded above their 200-day moving average, down from about 70% at the end of July. A rising index does not necessarily mean a broadly healthy market: when fewer stocks drive the gains, the market depends more on a small number of highly capitalized companies.
US stock market outlook: strong indexes, fragmented market
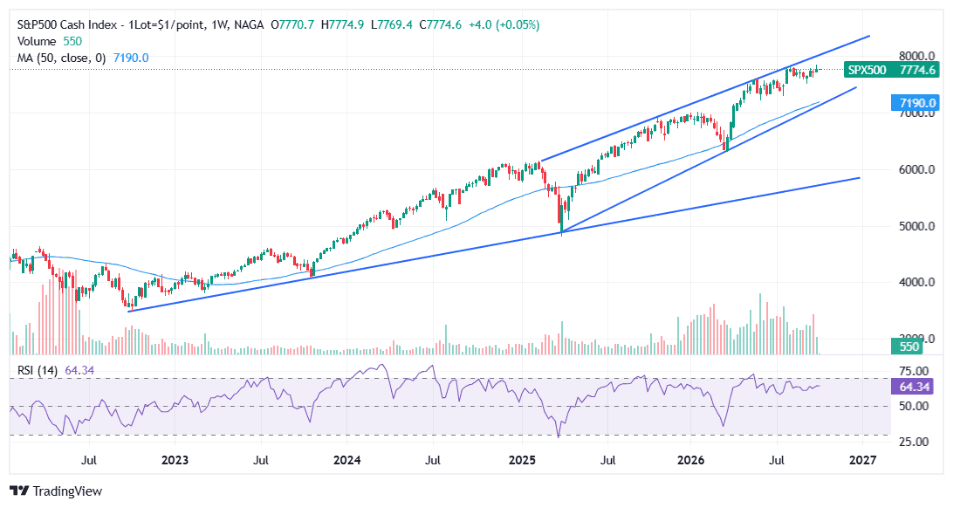
In Frank Walbaum's view, US equities remain one of the hardest areas to assess. The S&P 500 and the Nasdaq 100 continue to show strength, but the underlying market is much more fragmented, with dividend-oriented stocks comparatively weak and the Dow lagging the technology-heavy indices.
Past performance is not indicative of future results.
The AI narrative remains the main driver. If expectations around AI investment, earnings growth and productivity hold, technology stocks can keep supporting the indices; if the story begins to fade, the risk of a correction could rise quickly.
"I'm looking beyond the index price — if dividend-paying stocks continue to weaken while AI demand starts to fade, the rally becomes increasingly vulnerable to a larger correction." — Frank Walbaum, Market Analyst, NAGA
A healthier rally would need broader participation across underlying sectors, rather than continued concentration in a handful of AI leaders.
Earnings remain the bulls' strongest argument: bank estimates put 2026 S&P 500 earnings growth at roughly 24–32%. Year-end targets from 20 major brokerages range from 7,400 (BofA) to 8,100 (Citi, UBS, HSBC), with a median of 8,000, which implies only modest upside and leaves little room for disappointment.
What could trigger a stock market correction in Q4
The bullish scenario holds as long as risk appetite stays strong and earnings expectations keep supporting valuations. NAGA's outlook names six conditions that, in combination, would trigger the bearish scenario:
- fading AI momentum
- weaker earnings expectations
- rising bond yields
- stronger-than-expected inflation
- renewed dollar strength
- deteriorating market breadth
Yields deserve particular attention. The US 10-year Treasury yield rose 85 basis points in Q3 to 5.29%, its largest quarterly increase since 2009, which raises the discount rate applied to equity valuations. A temporary dollar correction, on the other hand, could support stocks and other risk assets. NAGA's Stock Market Crash Prediction examines the downside cases in more detail.
Q4 seasonality: what history says in a midterm year
History is on the bulls' side in the fourth quarter, and particularly so in midterm-election years such as 2026.
Statistic Value Average S&P 500 gain in Q4 since 1950 +4.2% (positive in about 80% of years) Average Q4 gain in midterm-election years since 1937 +6.6% Midterm years since 1950 with the S&P 500 higher 12 months later 19 of 19 (average ≈ +15%) Average "Santa Claus rally" gain since 1950 +1.3% (positive 78% of the time) Sources: Carson Group, J.P. Morgan Asset Management, Baird, LPL Research. Past performance is not a reliable indicator of future results.
When the S&P 500 was up 10–20% by the end of Q3, as it is this year, Q4 was positive in 18 of 21 cases (Carson Group). Seasonality is a tendency, not a forecast. In 2026 it competes with a 5% bond yield, an energy shock and narrow breadth, so the outlook reads it as a tailwind for the bullish scenario rather than a reason on its own.
European stock market outlook: why the DAX looks exposed
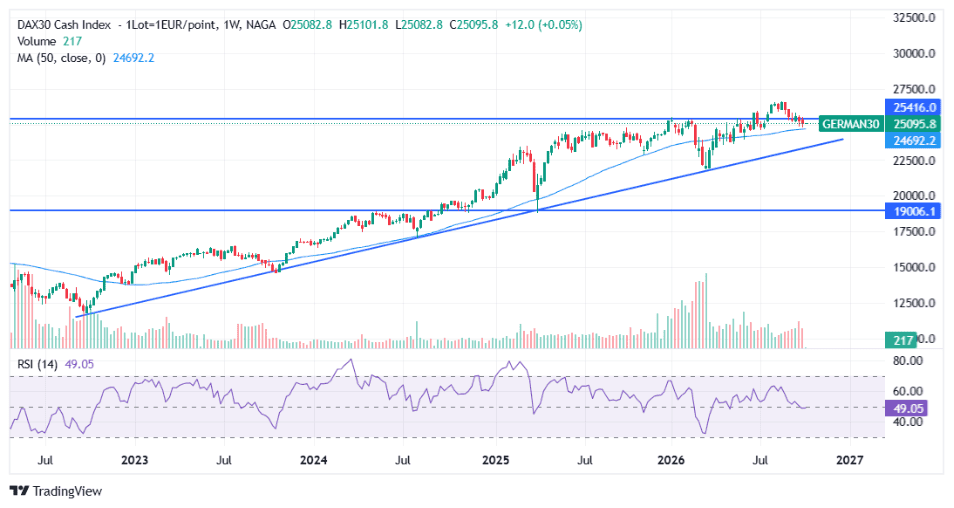
The German market looks less convincing than the US. The DAX gained only 0.8% in Q3 and 2.8% for the year to 30 September, against 12.1% for the S&P 500, and it trades below its August record of 26,628. Dispersion was wide, with SAP among the quarter's biggest winners and Infineon among the biggest losers.
Past performance is not indicative of future results.
Germany is particularly sensitive to global growth, industrial demand and energy costs. German gas storage near 59% leaves industry exposed if the winter is cold, and the Bundestag votes on the 2027 budget, with €118.7 billion of net borrowing, on 27 November. If global risk appetite holds, the DAX can participate; if sentiment deteriorates, it could weaken more than the major US indices.
"The DAX still looks vulnerable beneath the surface: the winter ahead, an unresolved Ukraine conflict and rising defence spending all add to the fundamental risks." — Frank Walbaum, Market Analyst, NAGA
With the August record at 26,628, the key level on the downside is 24,500 — a sustained break would significantly increase the risk of a deeper correction.
Elsewhere in Europe, the Euro Stoxx 50 fell 1.4% in Q3 and the FTSE 100 rose 0.3%, leaving both well ahead of the DAX for the year.
Three scenarios for stocks in Q4 2026
NAGA's outlook builds the quarter around three dollar-driven scenarios, with a risk-off environment the most likely at 50%.
Scenario Probability US equities DAX Dollar strength continues 25% Under pressure Under pressure Dollar correction 25% Supported Supported Risk-off environment 50% Under pressure Larger downside than peers Directional expectations only; not a recommendation.
The signposts for the risk-off case are the Big Tech results on 28–29 October, Nvidia's results on 17–18 November, market breadth and 10-year yields above 5.5%. For a dollar correction, weak payrolls on 6 November and 4 December and cooler inflation would be the first signs.
Key equity levels and dates for Q4 2026
The levels below come from Frank Walbaum's analysis and the NAGA platform charts, and the dates are the ones most likely to move equities.
Market Support Resistance S&P 500 7,600 7,845 (intraday record) DAX 24,500 26,628 (record) US 10-year yield 5.00% 5.50%
Date Event 13 October Q3 earnings season opens with the major US banks 14 October US CPI (September) 28 October FOMC decision 28–29 October Microsoft, Alphabet, Meta and Amazon results (expected) 3 November US midterm elections 17–18 November Nvidia Q3 results (expected) 9 December FOMC decision with new projections 11 December US government funding deadline Sources: Frank Walbaum; NAGA trading platform; company investor-relations pages. Dates subject to change.
Levels are reference points, not targets, and the reaction around them matters more than the level itself.
More NAGA stock market forecasts
This outlook sets the quarterly framework, while NAGA's forecast pages follow each index and theme in more detail:
- S&P 500 Forecast and Price Prediction
- Nasdaq 100 Forecast and Price Prediction
- Dow Jones Forecast and Price Prediction
- DAX Forecast and Price Prediction
- IBEX 35 Forecast and Price Prediction
- Stock Market Crash Prediction
- Best Stocks to Buy, Best ETFs to Invest In and 5 Undervalued European Stocks
- NAGA Group Stock Forecast (NAGA is a brand of The NAGA Group AG; see the conflict-of-interest note in the full report)
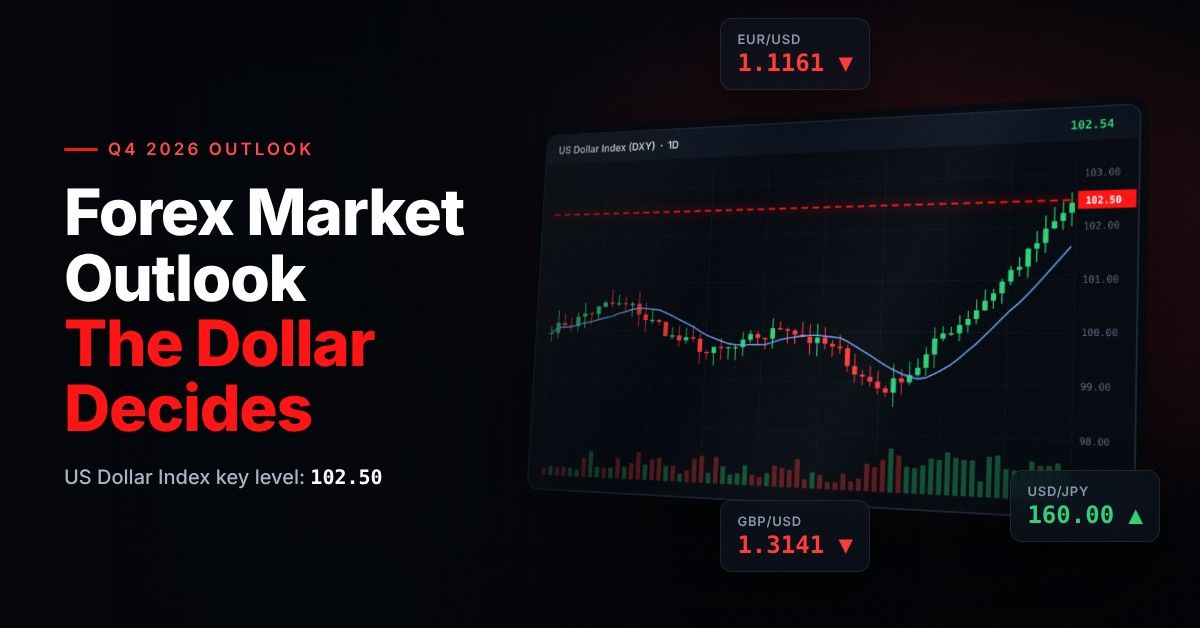
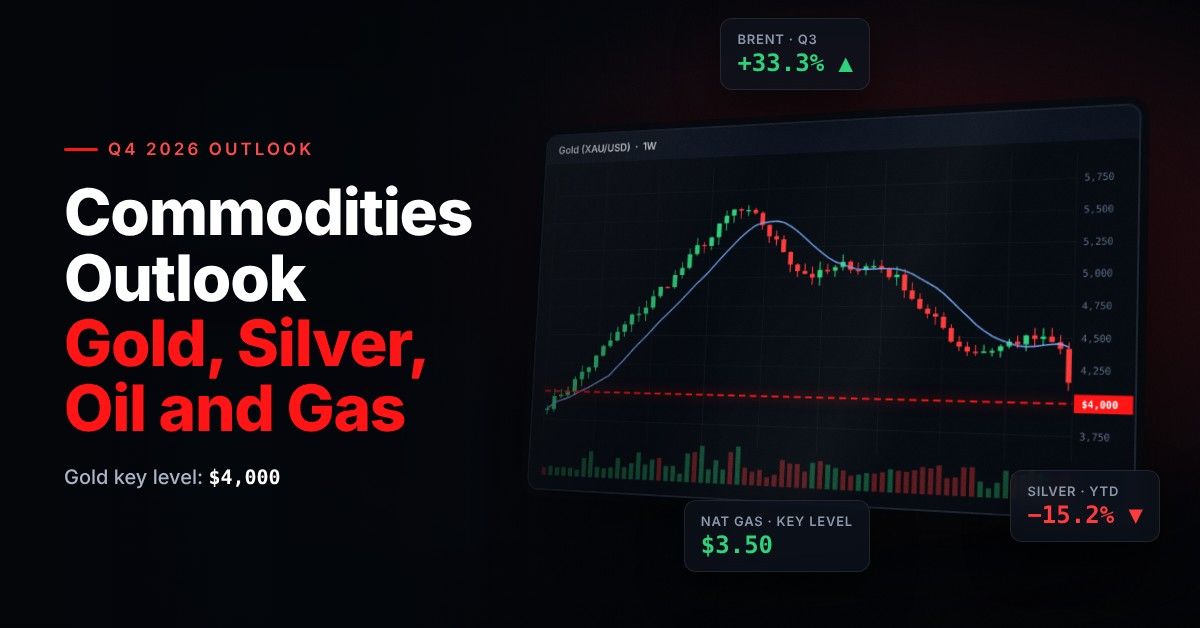
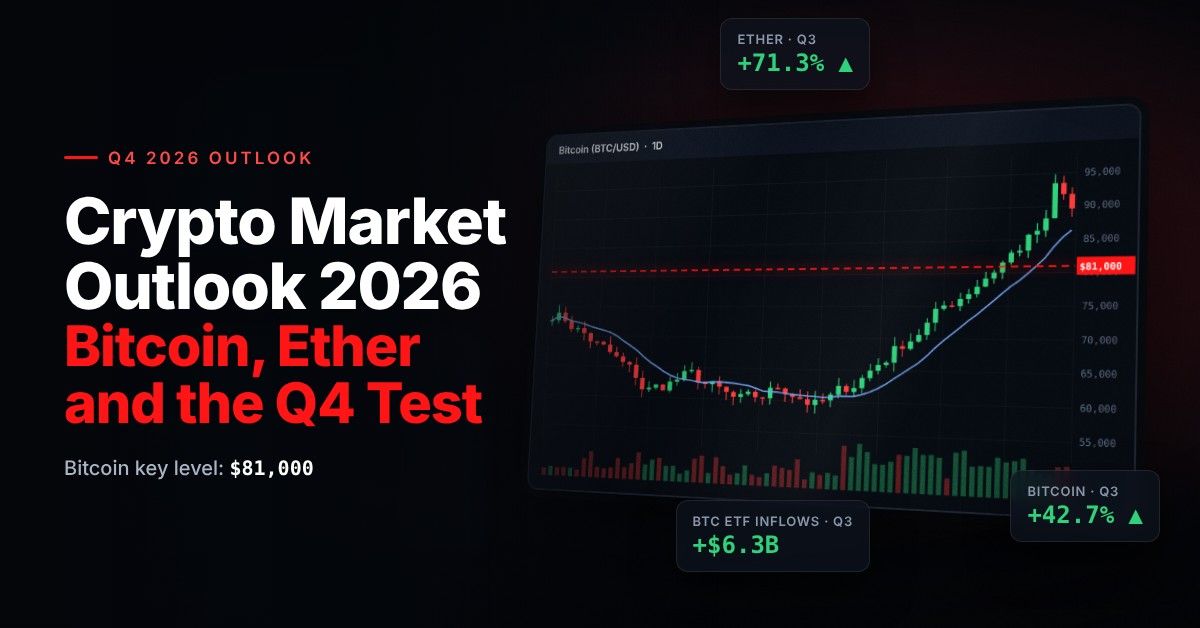
The same quarter is covered for other markets in NAGA's forex market outlook, commodities outlook and crypto market outlook for 2026.