


The outlook opens with US indices at record highs, the Federal Reserve hiking for the first time since 2023, the US 10-year Treasury yield above 5% and Brent crude near $100. Beneath those headlines, Walbaum finds a market that is narrower and more fragile than it looks, and in which the dollar has turned higher again since early September.
Q4 2026 market outlook — key takeaways
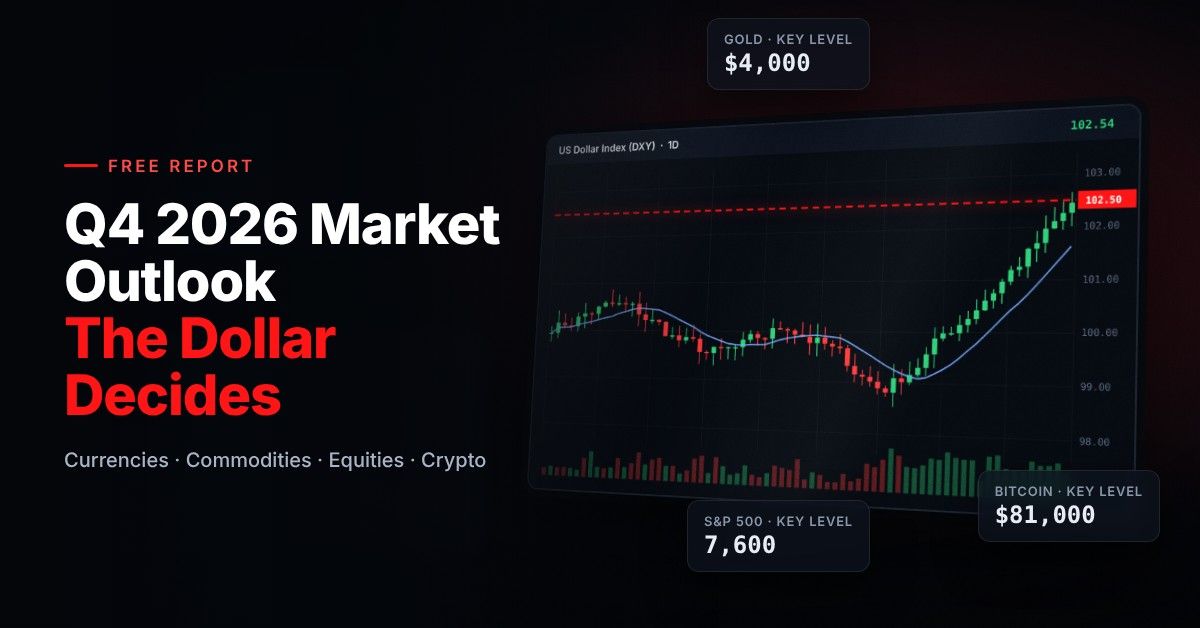
- The dollar sets the tone. The long-term trend remains bullish, and a sustained break above 102.50 on the US Dollar Index would confirm another leg higher. After a sharp September rally, a temporary correction is possible.
- The Fed is caught between inflation and jobs. Walbaum's base case is a hold in October and a hike in December, after the US 10-year yield jumped 85 basis points in Q3 to 5.29%.
- Gold holds its long-term uptrend above $4,000. Brent's $100 level remains the reference for oil as the geopolitical premium fades.
- The equity rally is narrow. Only 46% of S&P 500 members traded above their 200-day average in early October. The key levels are 7,600 on the S&P 500 and 24,500 on the DAX.
- Crypto looks overbought after a strong Q3. Bitcoin gained 42.7%, its best quarter in more than two years, and $81,000 is the level that frames its uptrend.
- Risk-off is the most likely scenario, at 50%.
Download the free report (PDF) Open an account
CFD trading involves risk.
Three scenarios, one common denominator
Rather than relying on a single forecast, the report frames Q4 around three scenarios, each built on the US dollar:
- Risk-off environment (50%): weakening market breadth and a fading AI narrative trigger a broader correction. Equities fall, gold may weaken at first before safe-haven demand returns, and the dollar benefits.
- Dollar strength continues (25%): a break above 102.50 confirms dollar momentum, putting gold, silver and risk assets under pressure, with USD/JPY potentially above 160.
- Dollar correction (25%): weaker US data and a more dovish Fed soften the dollar, supporting gold, stocks and crypto.
On oil, Walbaum sees markets growing used to the conflict in the Gulf. "Markets get tired of wars," he writes. "The second wave of the Iran conflict pushed oil higher, but the reaction was clearly smaller than the first — a sign that the geopolitical premium is fading."
On crypto, he prefers patience after the rally: "I'd rather see a correction than chase an overbought market — healthier entries could give the next leg higher more room to run."
The dates to watch in the coming weeks
The report's Q4 calendar shows which events could decide between the scenarios:
- 28 October: Fed decision and the UK Autumn Budget
- 28–29 October: results from Microsoft, Alphabet, Meta and Amazon (expected dates), a test of the AI narrative
- 29 October: ECB decision
- 3 November: US midterm elections
- 6 November: US jobs report
- 10 November: US inflation data
- 17–18 November: Nvidia results (expected)
- 9 December: Fed decision with new projections, likely the most important event of the quarter
Inside the report
Over 12 chapters and 20 charts, the Q4 2026 Market Outlook covers the Q3 scoreboard, NAGA client positioning, the Fed and global central banks, the 5% bond-yield question, currencies, commodities, equities, NAGA Group shares, crypto, a risk radar, the full Q4 calendar and a key-levels dashboard. Market data are as of the beginning of October 2026.
For a closer look at each market, read the four outlook articles:
- Forex Market Outlook Q4 2026: The Dollar Decides
- Stock Market Outlook Q4 2026: Record Highs, Narrow Rally
- Commodities Outlook Q4 2026: Gold, Silver, Oil and Gas
- Crypto Market Outlook 2026: Bitcoin, Ether and the Q4 Test
The views are updated through the quarter in NAGA's forecasts and price predictions.
About the author
Frank Walbaum is a Market Analyst at NAGA, covering global currencies, commodities and equity markets. Before joining NAGA, he worked as a fund manager in a family office, specializing in the FX market.