

Markets are sending increasingly mixed signals. The US dollar is showing signs of weakness, which would normally offer support to equities and other risk assets, yet stocks are struggling to regain momentum, cryptocurrencies are correcting and precious metals are moving lower. At the same time, oil is trading around USD 99 per barrel, keeping inflation concerns firmly in focus.
The Nasdaq is hovering around 29,030, while the S&P 500 trades near 7,660. Both indices remain at elevated levels, but the recent weakness in technology stocks raises a question that investors can no longer ignore: is the market approaching a turning point, or are we simply seeing a correction within a broader uptrend?
Several forces are coming together. The AI investment boom is facing tougher scrutiny, the conflict involving Iran continues to influence energy prices and inflation, and the upcoming US midterm elections add another layer of political uncertainty. Meanwhile, the Federal Reserve's next policy decision on October 28 could provide an important signal for the direction of markets heading into November.
AI Spending: When Good News Is No Longer Enough
The latest weakness in technology stocks suggests that investors are becoming more selective about the AI story. Meta's sell-off amid concerns about the scale of its AI investment plans illustrates the problem: companies may be spending enormous sums to secure their position in the next technological revolution, but investors increasingly want to know when those investments will translate into sustainable returns.
This matters well beyond individual technology stocks. Large technology companies have become major drivers of both the Nasdaq and the S&P 500, meaning that weakness among a handful of market leaders can have an outsized impact on the broader indices. If concerns about AI spending spread to other major players, the pressure could intensify even if traditional blue-chip companies start to perform relatively well. Some dividend-paying stocks may even benefit as investors seek more defensive exposure.
The key question is whether capital is simply rotating away from expensive technology stocks or whether confidence in the broader AI growth story is beginning to weaken. If the latter gains traction, the correction could become more widespread, potentially affecting sectors that initially appear insulated from the technology sell-off. Banks, for example, could face additional pressure if weaker equities eventually affect financial conditions, investor confidence or expectations for economic growth.
Forex: Why Isn't Dollar Weakness Helping Risk Assets?
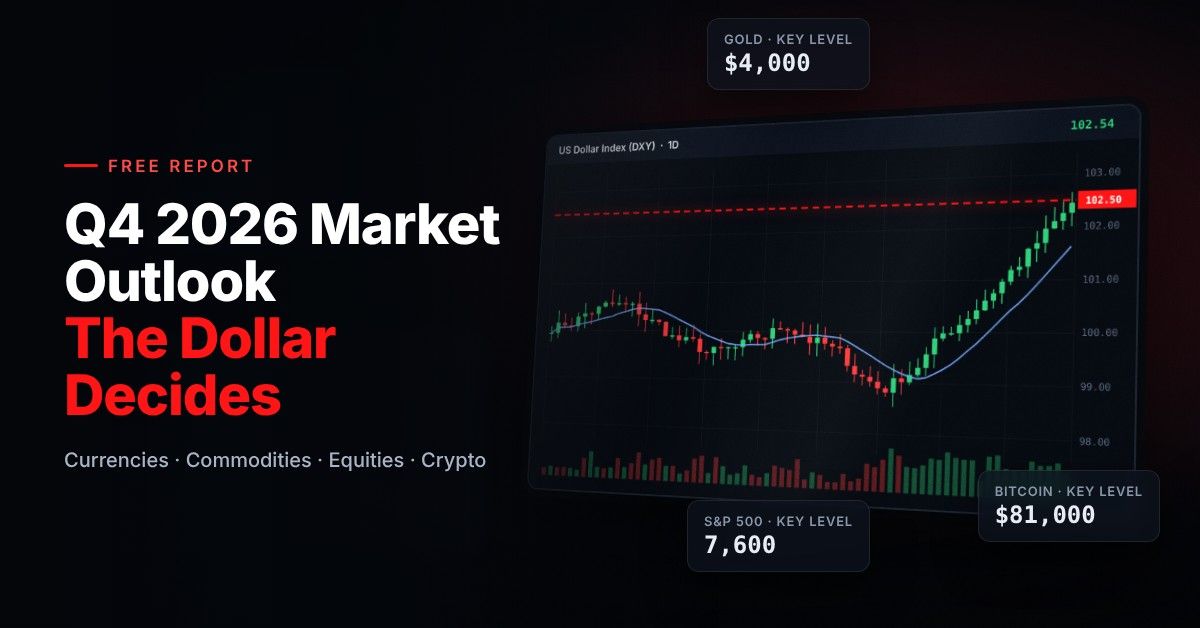
The forex market presents another puzzle. NAGA's DollarIndex is around 101.40, while EUR/USD trades near 1.1223 and AUD/USD around 0.7020. Although a weakening dollar would normally be supportive for risk assets, equities and crypto are failing to respond with convincing upside momentum.
That divergence deserves attention. It suggests that concerns about growth, inflation and valuations may currently outweigh the traditional support provided by a softer dollar.
EUR/USD remains under pressure, while AUD/USD is approaching a technically important area around its 50-day moving average at 0.7030. A sustained break above that level could signal improving risk appetite and open the door to further gains. A rejection, however, would suggest that buyers remain reluctant to commit and that the broader correction may have further to run.
The dollar's next move will also depend on how investors interpret inflation and the Fed's policy stance. If the greenback strengthens despite weakening equities, it could indicate that monetary-policy expectations and demand for liquidity are becoming more important than the usual relationship between the dollar and risk sentiment.
Inflation and Oil: The Fed's Difficult Balancing Act
Oil remains one of the most important variables in the current market environment. US-Oil is trading around USD 99.10, and persistent geopolitical risks mean energy prices could remain elevated even as investors question the sustainability of the broader economic expansion.
The inflation implications are significant. September US consumer prices rose 0.6% month-on-month, accelerating from 0.4% in August, while annual inflation reached 3.7%. Gasoline prices jumped 9.1% during the month, accounting for more than half of the monthly increase in headline CPI. Producer-price inflation has also accelerated, adding to concerns that price pressures may prove more persistent than policymakers had hoped.
For the Federal Reserve, this creates a difficult balancing act. Higher energy costs could keep inflation elevated just as financial markets are showing signs of strain. However, that does not automatically mean another rate hike is imminent: policymakers must also consider economic growth, employment and the risk that tighter financial conditions could amplify a market correction.
The key question is whether higher oil prices represent a temporary shock or the beginning of a more persistent inflation problem. If energy costs remain elevated and businesses pass those costs on to consumers, the Fed could find it harder to justify easing monetary policy.
Gold and Silver: Why Are Precious Metals Falling Too?
Gold is trading around USD 4,038 after breaking below the USD 4,100 support zone. The decline is particularly interesting because gold has often benefited from geopolitical uncertainty and concerns about inflation. Its current weakness suggests that those traditional drivers are being outweighed by other market forces, including positioning, liquidity needs and changing expectations for interest rates. Such moves are oftentimes amplified during the initial phase of a market correction.
If gold fails to recover the USD 4,100 area, the breakdown could encourage further selling. A recovery above that level, on the other hand, would suggest that buyers are returning and that the recent decline may prove temporary.
Silver faces a similar challenge, but its industrial exposure adds another dimension. Demand from solar technology, electronics and semiconductors remains important to its longer-term outlook, yet investors may become more cautious if expectations for industrial growth deteriorate. If the technology sector continues to weaken, silver could face pressure from both financial-market sentiment and concerns about future industrial demand.
The broader message is that precious metals are not automatically protected from a market correction. When investors reduce exposure across multiple asset classes, even traditionally defensive investments can decline.
Crypto: Following the Nasdaq or Finding Its Own Direction?
Bitcoin is trading around USD 81,140, while Ethereum is near USD 2,370. Both cryptocurrencies have been correcting alongside the Nasdaq, suggesting that the current weakness is not confined to traditional equity markets.
For now, the key question is whether the latest decline remains a correction within the broader trend or develops into a more sustained move lower. If technology stocks stabilise and risk appetite improves, crypto could recover as well. However, a deeper equity sell-off could encourage investors to reduce exposure to speculative assets, placing additional pressure on Bitcoin and Ethereum.
The next technical test will be whether the recent support zones hold. A successful defence could give the market room to recover, while a decisive break lower would weaken the bullish outlook and potentially trigger further selling.
Crypto therefore remains closely tied to the broader market mood. Until it demonstrates more independent strength, a sustained Nasdaq correction should be treated as a potential headwind rather than an opportunity that automatically benefits digital assets.
US Midterms Add Another Layer of Uncertainty
The upcoming US midterm elections on November 3 are another factor investors cannot ignore. The outcome could change the balance of power in Congress, with consequences for the administration's legislative agenda and the outlook for fiscal policy, regulation and trade.
For President Trump, the elections also carry political significance. A weaker result for Republicans could complicate the administration's ability to implement its agenda, potentially increasing uncertainty around future policy decisions. Markets will be particularly sensitive to developments that affect business confidence, government spending and international trade.
Elections do not necessarily trigger a sell-off, and historical market performance ahead of midterms is mixed. Nevertheless, political uncertainty can amplify existing concerns when valuations are high and investors are already questioning the sustainability of the rally.
Fed Preview: A Pause Now, but What About December?
The Federal Reserve's October 27–28 meeting is likely to be one of the main catalysts for markets next week. Following the recent acceleration in consumer and producer prices, policymakers face growing pressure to demonstrate that they remain committed to controlling inflation. At the same time, a correction in equities and uncertainty around the economic outlook could argue against tightening policy too aggressively.
The latest Reuters economist poll suggests that the Fed is likely to leave rates unchanged in October, with expectations for another rate increase shifting towards December. That would mean the immediate focus is not necessarily on a rate change next week, but on the message delivered by Chair Kevin Warsh and the Committee's assessment of the inflation outlook.
A pause would not automatically be bullish for stocks. If the Fed signals that further tightening may still be necessary because inflation remains stubbornly high, bond yields and the dollar could strengthen even without an immediate rate increase. That combination would create further headwinds for technology stocks, gold and other assets that are sensitive to financing conditions.
Conversely, a more reassuring message about the inflation outlook could help stabilise risk sentiment. Investors will therefore be listening closely for clues about how policymakers are balancing persistent price pressures against the risks of slowing growth.
There is an additional complication: the September PCE inflation report, the Fed's preferred inflation measure, is scheduled for October 29, the day after the decision. This unusual sequence means the Committee will have to make its October decision without that latest reading, while investors will receive another important piece of inflation information almost immediately afterwards.
Markets at a Turning Point?
The current environment is defined by conflicting signals. Dollar weakness should normally offer some support to risk assets, yet equities and cryptocurrencies are struggling to build momentum. Oil remains elevated, inflation is accelerating, and investors are becoming more demanding about the returns expected from AI investment. Even gold has broken below an important support level.
The S&P 500 around 7,660 and the Nasdaq near 29,080 are therefore worth watching closely. If technology stocks stabilise and the broader indices maintain their upward structure, the recent weakness could still prove to be a correction within a longer-term bullish trend. If concerns about AI spending intensify and selling spreads beyond technology, however, the risk of a deeper correction will increase.
Forex offers another important signal. AUD/USD around 0.7030 is approaching its 50-day moving average, while EUR/USD near 1.1223 remains under pressure. A recovery in the Australian dollar could indicate improving risk appetite, whereas another rejection at resistance would reinforce the cautious market picture.
For crypto, the immediate question is whether Bitcoin and Ethereum can hold their recent support zones despite equity-market weakness. For gold, the USD 4,100 level remains an important reference after the recent breakdown, while oil around USD 100 keeps inflation risks firmly in focus.
Markets may not have chosen their next direction yet, but the balance of risks is changing. The Fed decision next week, followed immediately by the latest PCE inflation data, could help determine whether investors are simply reassessing valuations or beginning to question the broader rally itself.
Source: Reuters, FT, Bloomberg